Getting a mortgage can be stressful and confusing;

it doesn't have to be, let us show you how. 
CALL US LET'S TALK

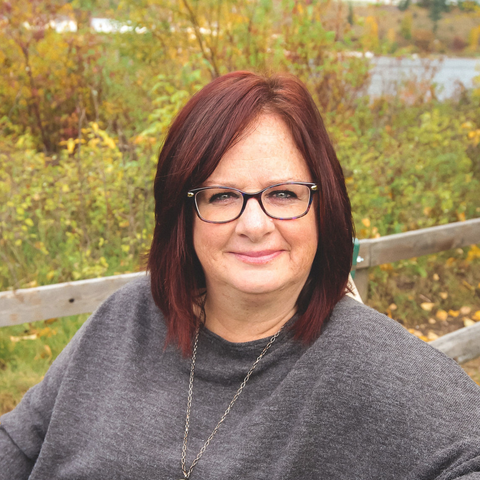
DIANE BUCHANAN

Mortgage Broker 

I started working in the mortgage industry in 2000 as my husband at the time was already a successful broker and needed an assistant. I was reluctant at first as I had 2 sons under the age of 5, but I found that I loved helping people finance homes and brokering wasn’t a 9-5 job so I could still spend time with my young family. Fast forward 20 years and I still love what I do.


My clients appreciate that I am available to answer their questions not only during regular business hours but outside of normal hours as well. I have been known to answer emails/calls/texts up to 8 pm at night and sometimes later, depending on their schedules. My clients will never have a ‘bank’ experience when working with me!


On a personal note, in the winter you will find me watching the Canucks, while in the summer I am cheering on the BC Lions. And just so you don’t think I spend all my time in front of the TV or at the stadium, I also enjoy spending time on the golf course.

Let's Run Some Numbers

Nice things our clients have said about working with us

SIGN CONSENT

We take your privacy very seriously. Here is a quick consent form that you can use to indicate you'd like to start the process in finding a mortgage with us! 

SIGN CONSENT

APPLY NOW

You've run some preliminary calculations, you've signed the consent form, the next step is to go through our online mortgage application.

APPLY

The Collective Mortgage Group provides mortgage services to loyal clients in a transparent environment, with an authentic voice, helping them feel protected, and save time and money.

LET'S TALK
April 2026 | A Delicate Balance
March 2026 | What Affects Rates
January 2026 | The Pause is the Point
Dec 2025 | Steady Means Strategy

MORTGAGE FINANCING


Whatever your mortgage needs; working with The Collective Mortgage Group , we have the mortgage services you're looking for. Click on any of the services for more information.

The power of working with us is that you don’t just get a Mortgage Broker, you get the care, attention, and knowledge of our entire team.

LET'S TALK

VALUED RELATIONSHIPS


As a Collective we’ve developed excellent relationships with Lenders, Realtors, Appraisers, Solicitors & Notaries, Home Inspectors, and many other service providers.

MORTGAGE ARTICLES


Looking for a little more information before getting in touch with us? No problems! Have a look through our mortgage blog where we share valuable information about mortgage financing and the home buying process. Once you're ready, feel free to connect with us in whatever way you feel comfortable. we're here for you! 
By Diane Buchanan September 16, 2026
Retirement doesn’t always mean a mortgage-free life anymore. And that’s okay. Between higher home prices, rising living costs, and longer life expectancy, many Canadians are choosing to retire with a mortgage or refinance later in life to create more flexibility. The goal isn’t perfection. It’s having options that actually support the life you want to live. If you’re thinking about how a mortgage fits into your retirement years, you’re not alone—and you’re not out of options. Why work with an independent mortgage professional? Because retirement financing is not one-size-fits-all. Unlike a single bank, an independent mortgage professional can look across multiple lenders and solutions to find what truly fits your income, equity, and long-term plans—not just what one institution offers. Mortgage options available in retirement Traditional Mortgage Solutions Many retirees still qualify for standard mortgages. Pension income, investment income, and other retirement sources can often be used to support an application. If you have good equity and solid credit, this is often the lowest-cost option. Reverse Mortgages For homeowners 55+, a reverse mortgage can unlock tax-free equity from your home with no monthly payments required. There’s no income verification or medical questions, making it a helpful option for those who want to improve cash flow while staying in their home. Home Equity Line of Credit (HELOC) A HELOC allows you to access your home equity as needed and only pay interest on what you use. Many retirees appreciate the flexibility and like consolidating income and expenses in one place. Private Financing Sometimes life throws a curveball. If timing, income, or credit create challenges, private financing can act as a short-term bridge. It’s not usually the first choice, but it can provide solutions when traditional lenders can’t. If you’re approaching retirement—or already there—and wondering how your mortgage fits into the picture, let’s talk. A clear plan can make retirement feel a lot more secure and a lot less stressful.
By Diane Buchanan September 9, 2026
What Online Mortgage Calculators Can—and Can’t—Tell You Online mortgage calculators are everywhere—and on the surface, they seem like a no-brainer. You plug in some numbers, and out pops what you can “afford.” Simple, right? Not quite. While the math itself is correct, the story behind those numbers is often misleading. Mortgage qualification isn’t just about numbers—it’s about context, risk, and lender policy. And that’s where calculators fall short. The Numbers Are Accurate—but the Picture Isn’t An online calculator can show you what a payment might look like at a given interest rate, or how making extra payments could reduce your amortization. That’s useful information! But when it comes to mortgage qualification , calculators don’t account for the many variables that lenders consider, such as: Your credit history and score Employment type (salary, self-employed, contract) Outstanding debts and monthly obligations Assets, savings, and down payment source The property type and location you’re buying Lenders evaluate all these factors through their internal risk models. That means two people entering the exact same numbers into a calculator could receive very different results when they actually apply for a mortgage. Why Online Calculators Can Mislead You When you see a “How much can I afford?” or “Mortgage Qualification” calculator online, it’s easy to treat the result as fact. But these tools don’t know your financial story—they only crunch the data you enter. A calculator can’t predict how a lender views your risk, how new mortgage rules apply to your file, or how things like spousal support, car loans, or variable income will impact approval. In short: calculators estimate payments, not qualification . Use Calculators the Right Way Don’t get us wrong—online calculators still have value. Use them to explore different “what-if” scenarios: How do payments change with different down payment amounts? How would a rate increase affect affordability? What if you added $100 a month to your payments? These tools are great for helping you understand your comfort zone. Just remember: they’re a starting point, not a green light. The Real First Step: Get a Pre-Approval If you’re serious about buying a home, skip the guesswork and get a mortgage pre-approval . It’s quick, free, and gives you real-world clarity on what you can afford. A pre-approval looks at your full financial picture—income, credit, debts, assets—and provides a framework for your purchase price, payment range, and rate options. It’s the only way to get a reliable answer to the question, “What can I really afford?” Final Thoughts Online calculators are convenient, but they can’t replace expert advice. Think of them as a starting point, not a solution. A professional mortgage broker can interpret the numbers, navigate lender policies, and tailor your financing strategy to your actual situation. If you’d like help understanding your true buying power—or want to get pre-approved with confidence— reach out anytime . I’d be happy to walk you through your options and help you make sense of the numbers.
By Diane Buchanan September 2, 2026
The Bank of Canada announced today that it is holding its target for the overnight rate at 2.25%, with the Bank Rate at 2.5% and the deposit rate at 2.20%. While Canada's economic recovery is broadening, a new layer of uncertainty has entered the picture. Here is what happened and what it means for your mortgage.

GET IN TOUCH

Contact Us